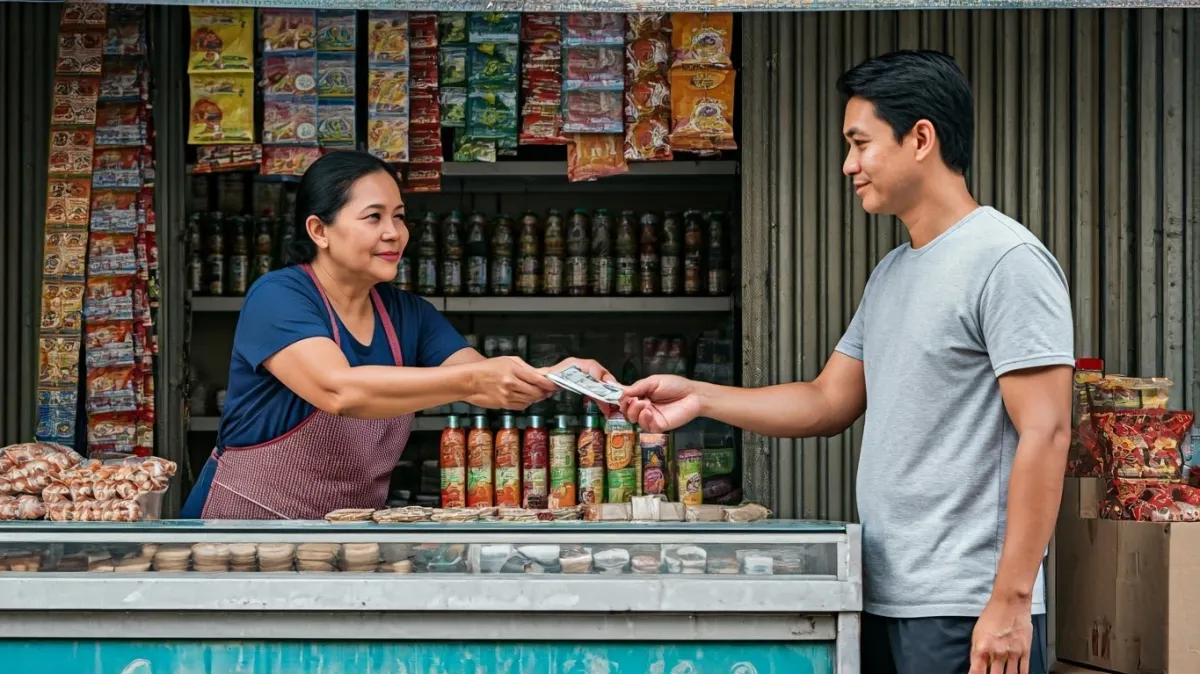
Sari-sari stores lead as Filipino shoppers remain cautious
Shoppers are switching to smaller packs and more affordable brands
Filipino shoppers are becoming more deliberate with their spending as higher prices and weaker consumer sentiment put pressure on household budgets, according to Worldpanel by Kantar's Asia Pulse Q2 2026 report.
FMCG value growth remained at 1.6%, although shoppers are finding it harder to expand their baskets.
As inflationary pressures persist, consumers are buying from fewer categories and reducing the volume of products in their baskets.
Downtrading also continues, with shoppers choosing smaller pack sizes and more affordable brand alternatives.
Shoppers are also shifting towards retail formats that better fit their everyday budgets.
Spending in hypermarkets and supermarkets has softened, whilst sari-sari stores have held firm.
Sari-sari stores remained the leading retail channel, accounting for 40% of total market value in Q2 2026, slightly down from 41% in Q2 2024 but up from 39% in Q2 2025.
Hypermarkets and superstores held the second-largest share at 26%, down from 27% in Q2 2024 but unchanged from Q2 2025.
Proximity channels, including discounters and convenience stores, also continue to grow as shoppers prioritise value and manage their spending more carefully.



 Read Here
 Advertise
 Sign Up